What Happens to the Home When a Parent Can No Longer Live Alone? Toronto Family Guide


Overview & Quick Facts
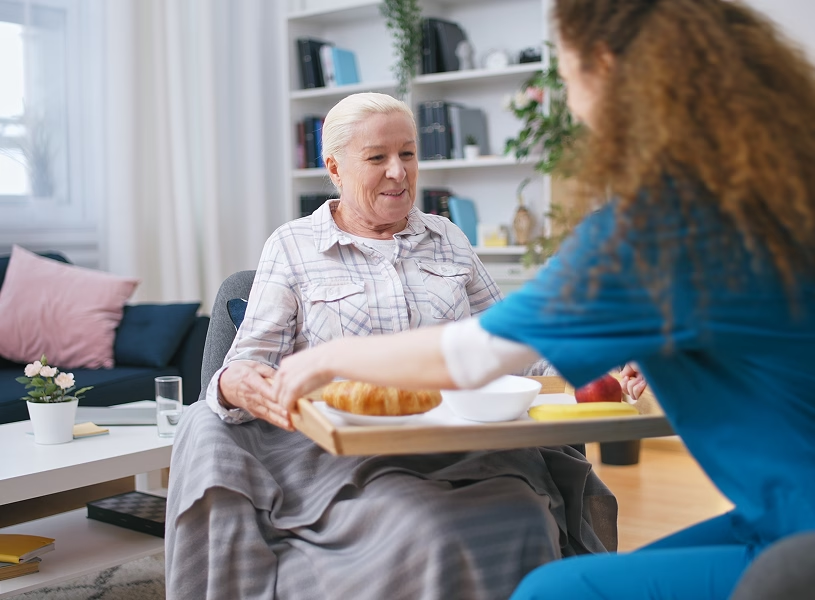
The moment an aging parent can no longer safely live alone in their Toronto home requires systematic family decision-making. Factors such as frequent falls, cognitive decline, physical mobility limitations, or home maintenance challenges necessitate evaluating care options alongside real estate strategy.
- The Issues: Assessing home safety risks, evaluating private home care versus moving to Assisted Living or Long-Term Care (LTC), verifying legal signing authority (Power of Attorney), and avoiding municipal Vacant Home Tax penalties.
- Care & Transition Supports: Synchronizing real estate steps alongside Ontario Health atHome care coordinators, occupational therapists, physicians, estate lawyers, and certified Senior Move Managers guarantees senior welfare.
- Core Strategy Summary: Families typically evaluate two primary paths: adapting the property with 24/7 home care or liquidating real estate to fund structured senior living. Selling the family home converts real estate into liquid capital, eliminating injury risks and property maintenance burdens while funding long-term care.
Pros and Cons: Strategic Opportunities vs. Organizational Risks
Choosing whether to sell the family home or maintain the property with in-home care requires balancing senior medical needs against long-term financial resources.
Pros of Selling the Home to Fund Care:
- Enhanced Senior Safety: Transitioning into a specialized retirement residence provides 24/7 medical supervision, dining services, and mobility assistance, removing household fall hazards.
- Capital Liquidity for Care: Liquidated real estate proceeds establish an investment pool capable of funding private Toronto retirement residence fees or LTC accommodation rates.
- Relief for Family Members: Adult children are relieved from serving as full-time caregivers and property managers, preserving healthy family relationships.
- Elimination of Property Expenses: Stops ongoing property taxes, utility bills, home insurance premiums, and emergency structural repair costs.
Cons and Organizational Risks of Delay:
- Prohibitive 24/7 Home Care Costs: Retaining the home while hiring private 24/7 in-home personal support workers can deplete liquid capital faster than residence placement.
- Risk of Lost Signing Authority: Delaying action until a parent completely loses mental capacity without an executed Power of Attorney prevents selling the home without court guardianship.
- Municipal Vacant Home Tax Exposure: Leaving the home empty while a parent is hospitalized or staying with family without filing a valid exemption triggers municipal tax penalties.
- Relocation Stress: Rapid or uncoordinated moves out of a long-held home can cause emotional distress if not managed by senior transition specialists.
Home Sale Strategy & Property Execution
Managing a property sale when a parent can no longer live independently requires a compassionate, highly documented approach that respects senior dignity.
- Core Real Estate Role: Shen Walji, SRES®, performs an independent Comparative Market Analysis (CMA) based on active TRREB MLS® data, establishing indisputable fair market value. Shen structures listing schedules to minimize senior disruption, keeping all formal communications aligned with the designated legal representative.
- Property Preparation Supports: Physical preparation is delegated entirely to verified third-party contractors. Shen Walji coordinates contents inventory, item sorting, junk removal, deep cleaning, handyman repairs, professional staging, and architectural photography.
Preserving Family Capital & Team Coordination
Safeguarding senior capital during a residential transition requires multi-disciplinary coordination among legal, tax, and real estate professionals in Toronto.
- Financial Advisors & CPAs: Structure 10-to-15-year care funding budgets, file Form T2091 with the Canada Revenue Agency (CRA) to secure the 100% Principal Residence Exemption, and optimize post-sale portfolio drawdowns.
- Estate & Real Estate Lawyers: Confirm signing capacity at contract execution, verify Continuing Power of Attorney for Property validity under the Ontario Substitute Decisions Act, apply for Toronto Vacant Home Tax exemptions, and execute the closing.
Family Decision Checklist
Adopting a structured workflow helps families determine the right housing path:
- Assess Care Urgency: Conduct a healthcare evaluation with physicians and an Ontario Health atHome coordinator to determine required care levels.
- Verify Legal Signing Authority: Confirm with an estate lawyer that an active Continuing Power of Attorney for Property is in place with real estate authority.
- Request an Independent CMA: Obtain a comprehensive market valuation from an SRES® specialist to project net liquid proceeds after transaction expenses.
- Establish a Care Funding Model: Calculate projected monthly costs for the chosen care arrangement and align property listing dates with residence move-in schedules.
Information Verification & Boundaries
Services are provided by Shen Walji, SRES® (Senior Real Estate Specialist). Content is for informational purposes and reflects real estate strategic planning based on TRREB MLS® market data. This material does not constitute legal, tax, or medical advice. For matters involving capacity assessments under the Ontario Substitute Decisions Act, care placement through Ontario Health atHome, RHRA regulations, CRA rules, or Toronto Vacant Home Tax exemptions, engaging qualified lawyers, tax advisors, and care coordinators is strongly recommended. Shen Walji can assist in coordinating with these licensed specialists.
FAQ
What happens to a house if a parent enters a long-term care home in Toronto?
The property remains in the parent's name unless sold or transferred by the owner or their legal Power of Attorney. If left unoccupied, the family must file for a Toronto Vacant Home Tax exemption and maintain vacant property insurance while deciding whether to sell or rent.
Can a child sell a parent's home if the parent can no longer live alone?
Only if the child holds a registered Continuing Power of Attorney for Property that gives real estate authority and the parent lacks capacity, OR if the parent retains capacity and voluntarily signs the real estate listing agreement. Children have no automatic legal right to sell a parent's home simply because the parent can no longer live alone.
How do families pay for retirement residences if the home hasn't sold yet?
Families can utilize liquid savings, secure a short-term real estate bridge loan, or negotiate deferred move-in payment schedules with private retirement homes until closing funds are disbursed by the real estate lawyer.